Article
Do You Qualify? 10 Life Events That Trigger Special Enrollment
August 18, 2026
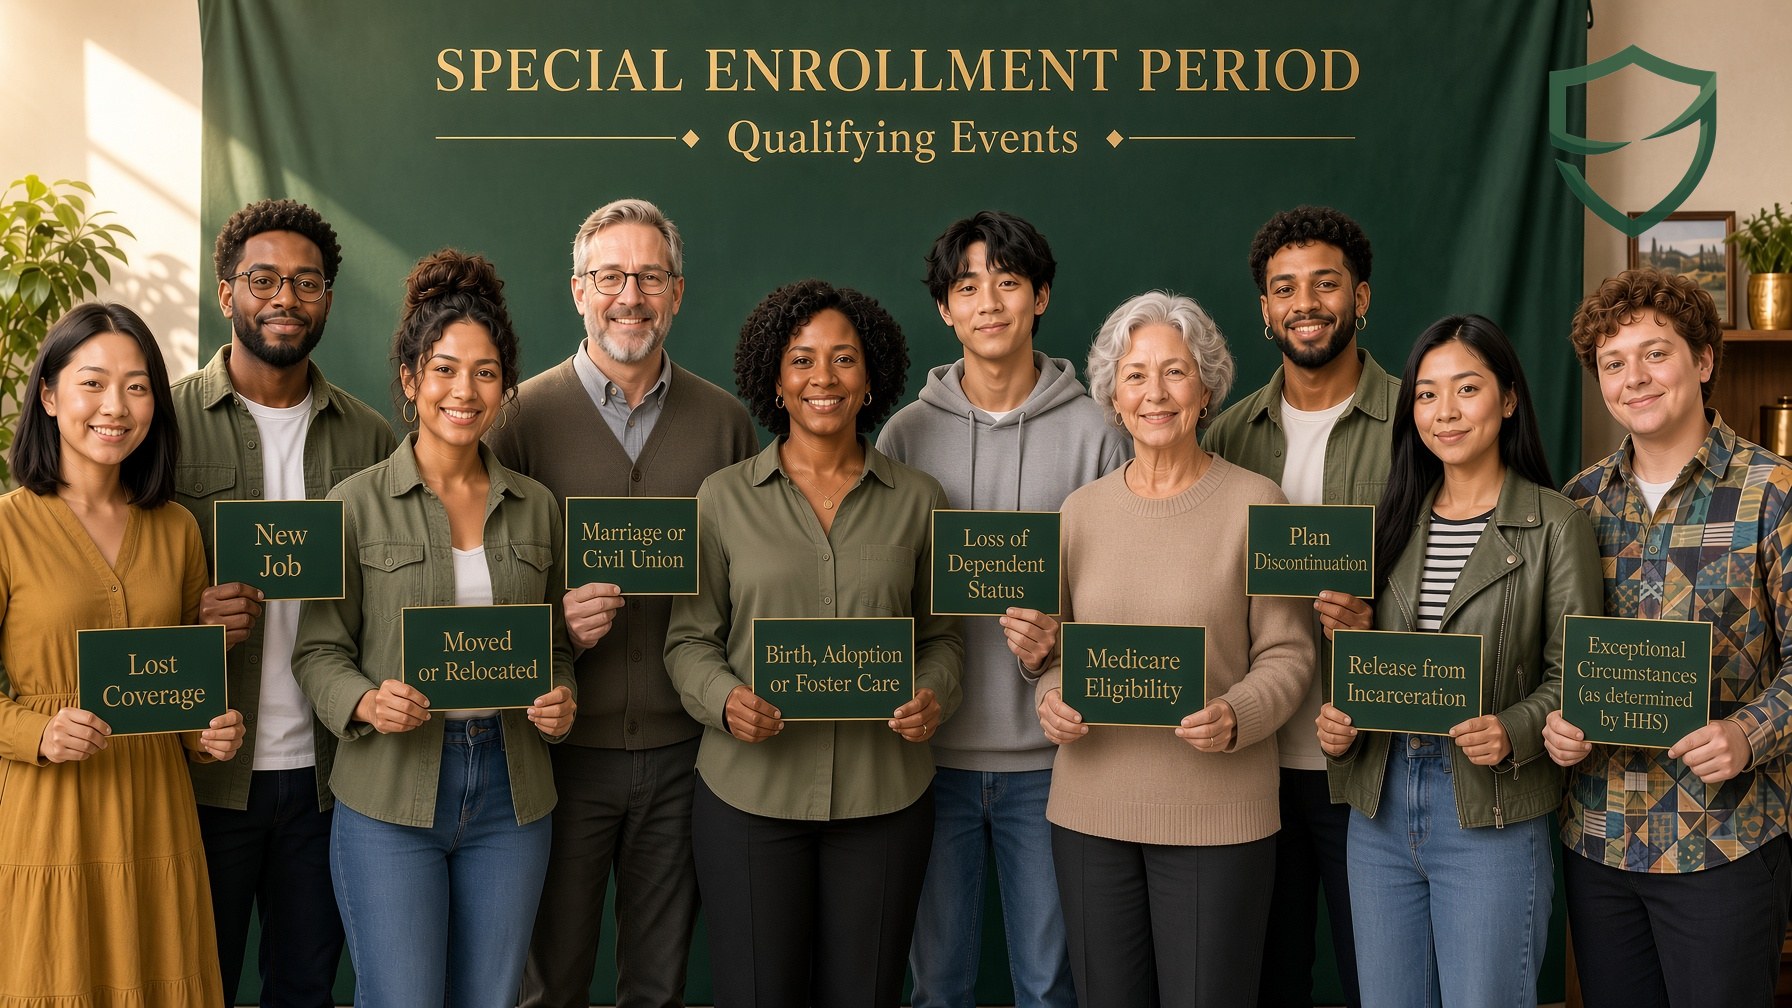
Ten life events that open a 60-day Special Enrollment Period, how the clock is measured for each one, the documents you will be asked for, and what to do if your window has already closed.
Missing Open Enrollment does not mean you are stuck without coverage for the year. If something significant changed in your life, you may qualify for a Special Enrollment Period (SEP), a 60-day window to enroll in or change a health plan outside the annual deadline.
Below are ten of the most common triggers, how the clock is measured for each, and the documentation you should have ready.
How long is a Special Enrollment Period?
Sixty days for most qualifying events. What varies is the day the count starts, and that is where people lose their window. Some events also let you apply up to 60 days in advance, which is almost always the better move because it prevents a gap.
1. Losing job-based health coverage
Quitting, being laid off, being fired, or having hours cut below the plan threshold all count. The 60 days run from the date coverage ends, not the date you left. You can also apply in the 60 days before it ends. Proof: a termination-of-coverage letter or COBRA election notice.
2. Turning 26 and rolling off a parent plan
Aging off a parent's plan is a qualifying event. Plans typically end on your birthday or at the end of that month, and your plan documents decide which. Enroll before the end date so nothing lapses. Proof: the insurer's letter stating the termination date.
3. Getting married
Marriage opens a 60-day window from the wedding date, and it lets you combine or compare households. Newly married couples often find one spouse's plan is materially better for both. Proof: a marriage certificate.
4. Divorce or legal separation that ends coverage
Divorce itself is not always the trigger. Losing coverage because of it is. The clock runs from the loss-of-coverage date. This is also the moment to update life insurance beneficiaries, which is the single most commonly forgotten step after a divorce. Proof: a divorce decree plus the coverage termination notice.
5. Having a baby, adopting, or placement for foster care
Coverage for a new child is generally retroactive to the date of birth, adoption or placement, and the window is 60 days. Add the child promptly. Proof: a birth certificate, adoption paperwork or placement documentation.
6. A permanent move
Moving to a new ZIP code, county or state can qualify you when it changes your available plans, and when you had qualifying coverage for at least one of the 60 days beforehand. In the DC, Maryland and Virginia area, a short move can change your Marketplace, your plan options and your subsidy amount. Proof: a lease, deed, utility bill or employer letter, plus proof of prior coverage.
7. A death in the household that ends coverage
Losing coverage because the policyholder died is a qualifying event, measured from the loss-of-coverage date. Proof: a death certificate and the coverage termination notice.
8. Losing Medicaid or CHIP eligibility
If your income rises above the threshold or a redetermination ends your enrollment, you get a window to move to a Marketplace plan. Proof: the termination notice from the state agency.
9. A change in income that changes your eligibility
Income changes can move you between Medicaid, subsidized Marketplace coverage and cost-sharing reductions. Even when a change does not open a new window, you are expected to report it, because advance premium tax credits are reconciled on your tax return.
10. Gaining citizenship, lawful presence, or leaving incarceration
Becoming a United States citizen or lawfully present resident, or being released from incarceration, opens an enrollment window. Moving to the United States from a foreign country or a United States territory qualifies without the usual prior-coverage requirement.
Other triggers worth knowing
- Your plan is discontinued or your insurer leaves your area.
- Your employer's coverage becomes unaffordable or stops meeting minimum value.
- Gaining or becoming a dependent through a court order.
- Enrollment errors by the Marketplace, an insurer or an agent.
- Members of federally recognized tribes may enroll monthly.
- Medicaid and CHIP have no annual deadline: you can apply any time you qualify.
What if none of these apply to me?
Then your date is November 1, the start of Open Enrollment, for coverage beginning the following year. In the meantime, Medicaid or CHIP eligibility is worth checking, and if you have a family a life insurance review is not deadline-bound at all.
What if my 60 days already expired?
Options narrow but rarely disappear entirely. Depending on your household this can include Medicaid or CHIP, a spouse's employer plan window, or a short-term product as a stopgap where it is available. Short-term plans are not required to cover pre-existing conditions or essential health benefits, so treat them as a bridge, not a destination.
Check your eligibility in two minutes
If you are unsure whether your situation qualifies, or which day your 60 days started, the fastest answer is the SEP eligibility check on this site. It asks three questions and tells you your window.
You can also call (571) 571-1491 or email austinw@scudobenefitsgroup.com. There is no cost for my help, and I respond within 24 hours.
Austin Wilson, licensed independent insurance agent serving DC, Maryland, Michigan, Ohio, Texas, Virginia and Florida. NPN 22224104, Virginia License #1585974. Scudo Benefits Group is an independent insurance agency and is not affiliated with or endorsed by any government agency or the federal Health Insurance Marketplace. This article is general information, not insurance, legal or tax advice. Eligibility, plan availability and pricing vary by state, county and carrier.
Related reading: for every deadline, subsidy rule, and plan decision in one place, see Open Enrollment: Every Deadline, Rule, and Decision You Need to Know.
Authored by Austin Wilson
Licensed insurance agent and founder of Scudo Benefits Group, serving DC, FL, MD, MI, OH, TX and VA. NPN 22224104 · VA License #1585974
Questions about your coverage? Call (571) 571-1491 or email austinw@scudobenefitsgroup.com.